

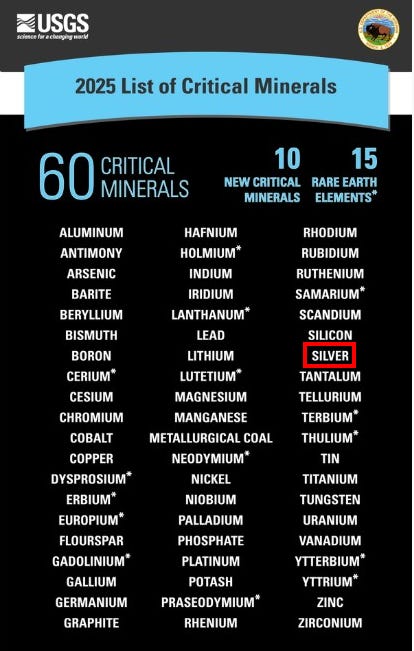
In a move that will reshape global silver markets for decades to come, the United States has officially added silver to its 2025 List of Critical Minerals. This designation places silver alongside lithium, uranium, and rare earth elements as materials essential to national defense, national security, economic prosperity, and technological advancement.
What appears to be a simple bureaucratic classification is actually a seismic shift that transforms silver from a precious metal into a strategic national asset; with profound implications for supply, demand, and price.
The timing of this designation is no coincidence. Silver has been in supply deficit for five consecutive years, moving into its sixth year of structural shortfall just as industrial demand reaches unprecedented levels.
The U.S. government’s recognition of silver as critical comes at the precise moment when the metal’s unique supply-demand dynamics create the most explosive setup in modern commodity history.
The Supply Crisis That Changes Everything
Silver’s supply structure is fundamentally different from every other critical mineral, creating constraints that no amount of government intervention can quickly resolve.
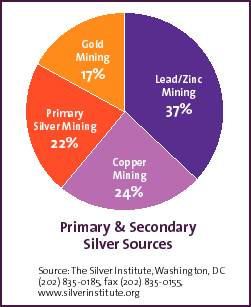
More than 70% of all silver mined globally comes as a byproduct of other mining operations; primarily lead, zinc, copper, and gold extraction. This means that silver supply is largely determined by demand for other metals, not by silver’s own price.
This byproduct nature creates a unique problem: unlike other commodities where higher prices typically incentivize increased production, silver’s supply response to price increases is severely limited.
When copper demand drives copper mining, silver comes along as a secondary benefit. When copper demand falls, silver production falls regardless of silver’s price.
This disconnect between price and supply response is unprecedented among critical minerals.
The numbers are stark. Global silver mine production has remained essentially flat for over a decade, hovering around 850 million ounces annually.
Despite silver prices rising from $15 to over $48 per ounce in recent years, new primary silver mines have not materialized in meaningful numbers. The lead times for new mining projects, combined with the limited number of economically viable primary silver deposits, mean that supply constraints will persist for years regardless of price incentives.
The Demand Explosion & The Multiple Floors Under Silver
While supply remains constrained, silver demand is experiencing unprecedented growth across multiple sectors, creating what analysts describe as “multiple demand floors” that provide extraordinary price support.
Let’s dig into:
The massive demand pulls on silver
The new U.S. government stockpiling factor & likely trigger for a global stockpiling race
The global monetary awakening in the public
Converging forces on silver
And the strategic metal revolution…
